If you’ve been thinking about selling, you’ve probably seen plenty of headlines suggesting buyers have just about disappeared. But there’s a big difference between a slow market
Dated: February 3 2025
Views: 50
Have you been wondering whether you should keep renting or finally make the leap into homeownership? It’s a big decision, and let’s be real — renting can feel like the easier option, especially if buying a home feels out of reach.
But here’s the thing: a recent report from Bank of America highlights that 70% of prospective buyers fear the long-term consequences of renting, including not building equity and dealing with rising rents.
Maybe you’re feeling that too — concerned about where renting might leave you down the road, but still unsure if you'd even be able to buy right now. The truth is, if you’re able to make the numbers work, buying a home has powerful long-term financial benefits.
Let’s break down why homeownership is worth considering in 2025 and beyond, and how it can help set you up for the future.
Buying a home allows you to turn your monthly housing costs into a long-term investment. That’s because, as shown in data from the Census and the Department of Housing and Urban Development (HUD), home prices tend to increase over time (see graph below):
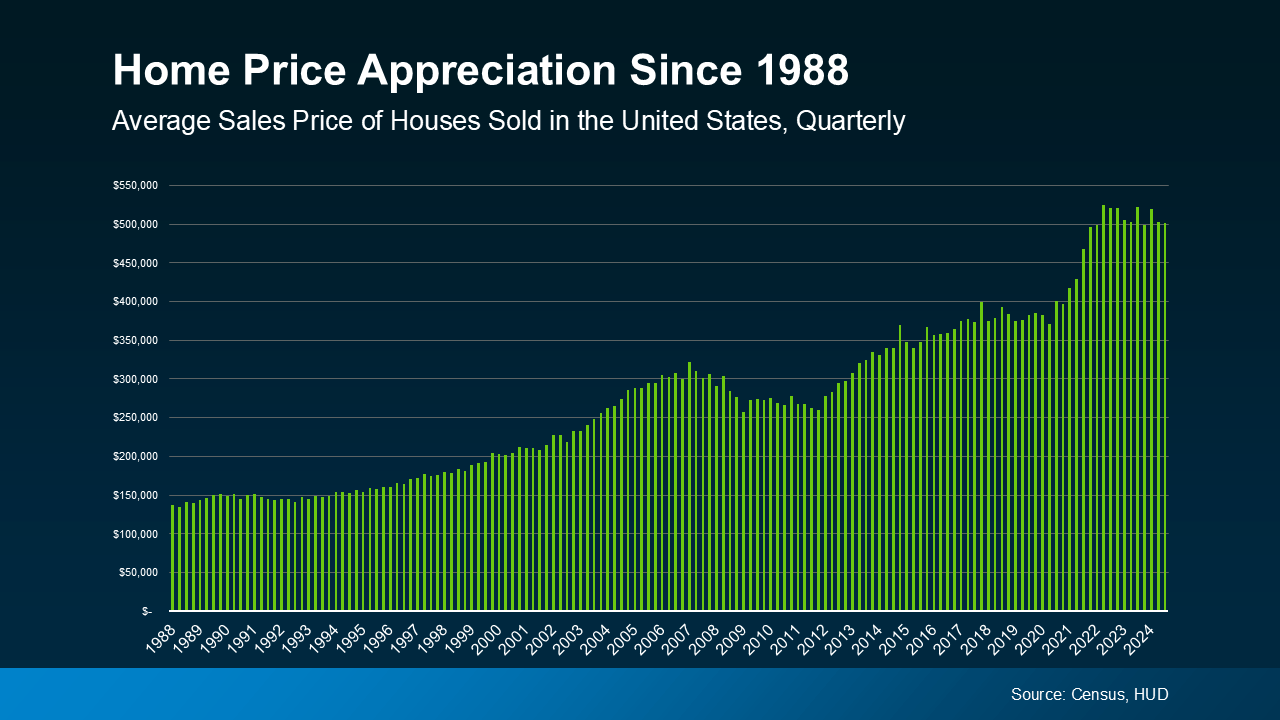 Rising home prices directly benefit homeowners. That’s because when you own a home, you build equity — meaning your ownership stake in your home grows as you pay down your mortgage and your home's value appreciates. And that, in turn, makes your net worth grow too.
Maybe that’s why, according to the National Association of Realtors (NAR), 79% of buyers believe owning a home is a good financial investment.
Renting may feel more affordable in the short term, especially right now with today’s home prices and mortgage rates. But the reality is, over time, rent almost always goes up too. Take a look at the data and you can see that play out. According to Census data, rents have significantly increased over the decades (see graph below):
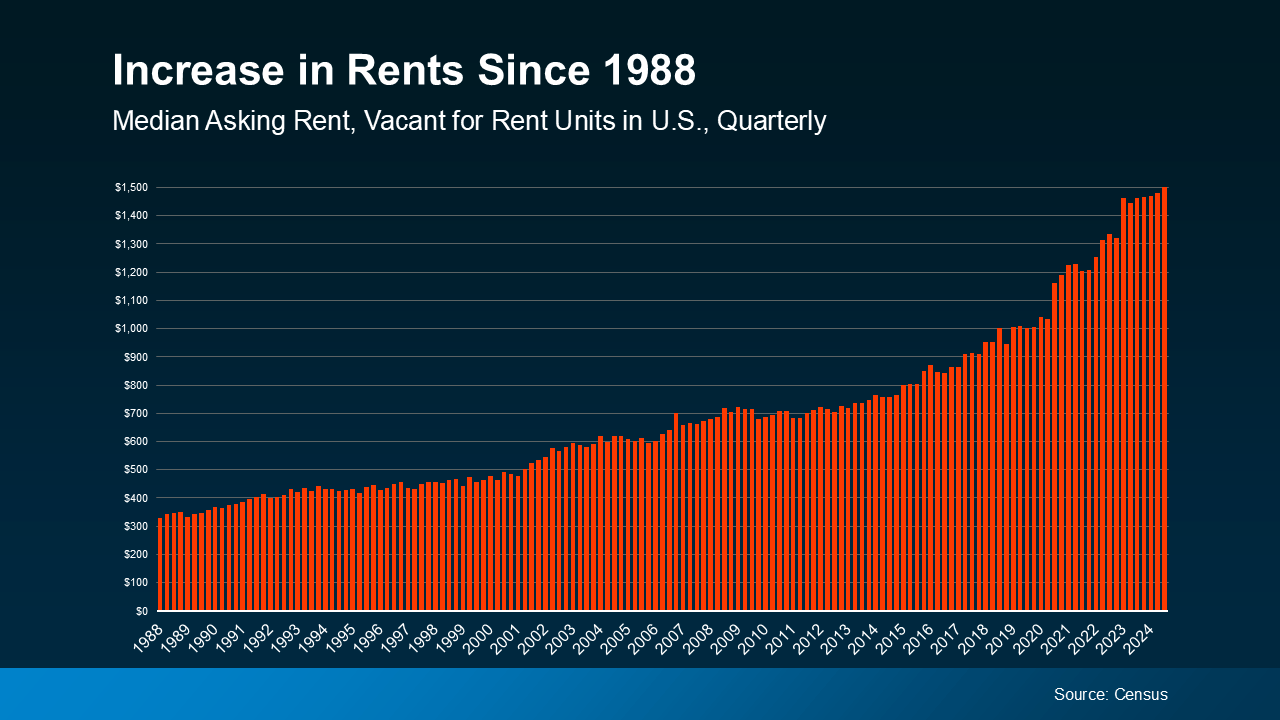 This means if you decide to rent, you’ll likely face growing expenses each time you renew or sign a new lease – and that’ll happen without building any wealth in return. Plus, those rising costs may make it harder to save up to buy a home down the road.
When you own a home, your payments are an investment in your future. Renting, on the other hand, means your money is gone for good — it helps your landlord build equity, not you.
Renting works for those not ready (or able) to buy today. But if you are able to make the numbers work, buying a home builds equity and sets you up for long-term financial success. So, even though renting may seem easier now, it can’t match the benefits of homeownership.
If you can afford it, take control of your financial future by making homeownership part of your plan. It’s an investment you won’t regret.
Do you want to see what starter homes are available in our market? Let’s connect today to explore your options.
I've dedicated my real estate career with connections to our "Heroes". Who are our Heroes? Those in the professions of the US Military, Police, Fire, Education, Medical, and Social Services, who self....
If you’ve been thinking about selling, you’ve probably seen plenty of headlines suggesting buyers have just about disappeared. But there’s a big difference between a slow market
If the first half of this year has left you feeling stuck, you’re not the only one. Mortgage rates stayed higher than people wanted. Affordability remained tight. And uncertainty overseas
Buying or selling a home is a big financial decision. And right now, it feels even bigger. Inflation is high, costs are high, and you want to be sure the timing is right before you make your move.
Saving for a down payment can feel like the hardest part of buying a home. And with affordability as tight as it’s been lately, it’s fair to wonder how anyone manages it right now. Here
 Based on information from California Regional Multiple Listing Service, Inc. as of September 27, 2026 5:06 AM UTC This information is for your personal, non-commercial use and may not be used for any purpose other than to identify prospective properties you may be interested in purchasing. Display of MLS data is usually deemed reliable but is NOT guaranteed accurate by the MLS. Buyers are responsible for verifying the accuracy of all information and should investigate the data themselves or retain appropriate professionals. Information from sources other than the Listing Agent may have been included in the MLS data. Unless otherwise specified in writing, Broker/Agent has not and will not verify any information obtained from other sources. The Broker/Agent providing the information contained herein may or may not have been the Listing and/or Selling Agent.
Based on information from September 27, 2026 5:06 AM UTC The information being provided by CRMLS is for the visitor's personal, noncommercial use and may not be used for any purpose other than to identify prospective properties visitor may be interested in purchasing. The data contained herein is copyrighted by CRMLS, CLAW, i-Tech MLS, PSRMLS and/or VCRDS and is protected by all applicable copyright laws. Any dissemination of this information is in violation of copyright laws and is strictly prohibited.
Any property information referenced on this website comes from the Internet Data Exchange (IDX) program of CRMLS. All data, including all measurements and calculations of area, is obtained from various sources and has not been, and will not be, verified by broker or MLS. All information should be independently reviewed and verified for accuracy. Properties may or may not be listed by the office/agent presenting the information.
